

Capricorn Metals Clears a Three-Year Wait for Its Second Gold Mine
Fund managers say Mt Gibson's long-awaited approval sets up a second low-cost production base and makes Capricorn a takeover prospect
30 Jun 2026 · 4 min read
In short
Capricorn Metals' Karlawinda mine produces at an industry-leading all-in sustaining cost of A$1,311 per ounce, Oracle Advisory Group says.
The Mt Gibson project's underground resource was upgraded 31% to 895,000 ounces, with development targeting 300,000oz annual production.
Mt Gibson finally received environmental and development approval in mid-2026 after three and a half years, clearing the path to a second mine.
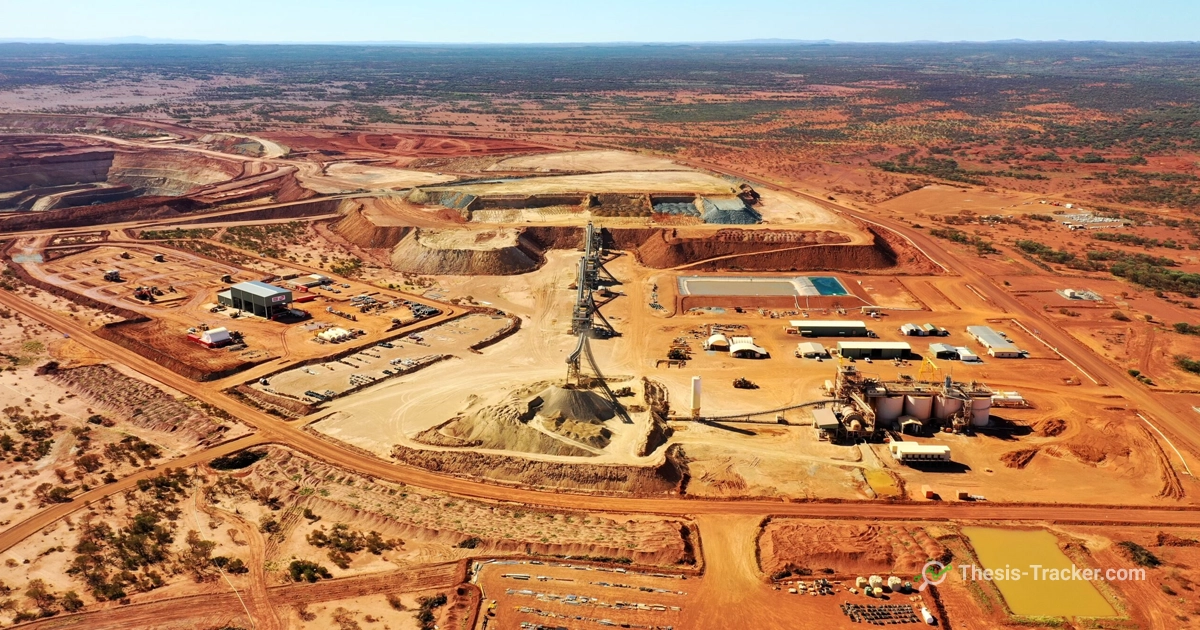
Western Australian gold producer Capricorn Metals built a reputation for consistency at its Karlawinda mine before a long-awaited Mt Gibson approval finally cleared the path to a second, larger production base after three and a half years of waiting.
A management team fund managers rate among the best
Blackwattle Investment Partners' October 2025 case rested first on the people: a core team that had worked together across three corporate ventures over 20 years, approaching every mine build and operation with a consistent discipline. Pendal Group's own October assessment pointed to a deliberate simplicity, operating almost exclusively in Western Australia where the team knows the regulatory regime, procurement channels and service providers, combined with a position among the lowest-cost gold producers in the country.
When we look for quality in mining businesses, there are two big things: the team and the asset. The team here would challenge any other. Some of the core team have worked together across three corporates now, over 20 years.
— Blackwattle Investment Partners, Article, October 2025
A resource upgrade at the development asset
Yarra Capital Management's November 2025 update reported a 31 per cent increase in the underground mineral resource estimate at the Mt Gibson project, lifting the resource to 895,000 ounces of gold and underscoring the long-term growth potential behind the company's target of reaching 300,000 ounces of annual production once Mt Gibson commences, on top of the roughly 120,000 ounces currently produced at Karlawinda. Oracle Advisory Group's December update highlighted Karlawinda's high margin profile at an all-in sustaining cost of A$1,311 an ounce, giving the company significant leverage to a rising gold price, alongside the acquisition of Warriedar Resources adding a further gold deposit near Mt Gibson.
A volatile quarter tests conviction
Paradice Investment Management's March 2026 update described an extraordinary run of volatility: the gold price and Capricorn shares rallied to fresh record highs in January, before a sharp February sell-off tied to an AI-related market drawdown, followed by an even sharper March decline. Perennial Partners quantified the damage, with shares down 25.3 per cent in March as gold itself fell 11.6 per cent, part of a broader sector-wide sell-off. Quest Asset Partners used the correction as an opportunity, adding to its position at what it viewed as a positioning-driven liquidity event rather than any fundamental change, with shares down 23 per cent for the quarter.
A hold thesis built on already-priced-in growth
Datt Capital and Acorn Capital both settled on a hold rating in April 2026, agreeing Karlawinda was a genuinely excellent, remarkably consistent asset under a high-quality management team, but arguing the growth potential from Mt Gibson was largely already reflected in the valuation while the project awaited permits. Alliance Bernstein took a more cautious view still, exiting its position given concerns the company was among the more exposed names in a potential fuel-rationing scenario.
I agree with all the points that Emanuel made. It's a really high-quality management team. Karlawinda is a fantastic asset, I often joke that it'd be the most boring place to work at on earth because it's just so consistent from one month to the next one quarter, and that's what's sort of driving the market's real love for the asset.
— Acorn Capital, Article, April 2026
A long-awaited approval finally arrives
Blackwattle Investment Partners' May 2026 update reported shares rallying 25 per cent after completion of the Federal environmental assessment for Mt Gibson, materially de-risking the permitting pathway that had held up the project. Totus Capital's June 2026 update confirmed the final milestone: after three and a half years, Capricorn finally received approval for its second Western Australian mine, a catalyst Totus described as making the company an enticing takeover prospect for larger gold producers once it operates two large, low-cost, long-life mines in a geopolitically attractive jurisdiction.
Questions
How cost-efficient is Capricorn Metals' Karlawinda gold mine?
Oracle Advisory Group said Karlawinda operates at an all-in sustaining cost of A$1,311 per ounce, a high-margin, low-cost profile that gives Capricorn Metals significant leverage to a rising gold price.
What is the status of Capricorn Metals' Mt Gibson project?
Totus Capital reported Mt Gibson finally received development approval in June 2026 after a 3.5-year wait, following completion of its Federal environmental assessment in May 2026, clearing the path for Capricorn's second large-scale Western Australian gold mine.
Why do fund managers see Capricorn Metals as a potential takeover target?
Totus Capital said that once Mt Gibson is operational alongside Karlawinda, Capricorn will have two large, low-cost, long-life gold mines in Western Australia, making it an enticing takeover prospect for larger gold producers.
16 managers, 24 comments, with each manager's latest recorded position.
See CMM