

Why fund managers keep buying Capstone Copper despite its guidance misses
Capstone Copper's Chile-based operations keep missing production targets, but fund managers say its valuation discount to peers is unjustified given its growth pipeline.
10 Jun 2026 · 6 min read
In short
Capstone Copper generates 100% of its revenue outside Australia, from copper mines in Chile, the United States and Mexico.
The company's Mantoverde Optimiser project will increase copper throughput by 40% and extend mine life to 25 years, at a cost of around US$170-176 million.
PM Capital argues Capstone's valuation discount to copper peers is not justified, despite a history of missing production and capital expenditure guidance.
Copper producer Capstone Copper operates entirely outside Australia despite its ASX listing, with Longwave Capital's June 2026 Newsletter noting 100% of FY25 revenue was generated from mines in Chile, the United States and Mexico, with offshore revenue rising around 48% year on year to US$2.36 billion, supported by a 22% increase in copper production.
Growth optionality tempered by a habit of guidance misses
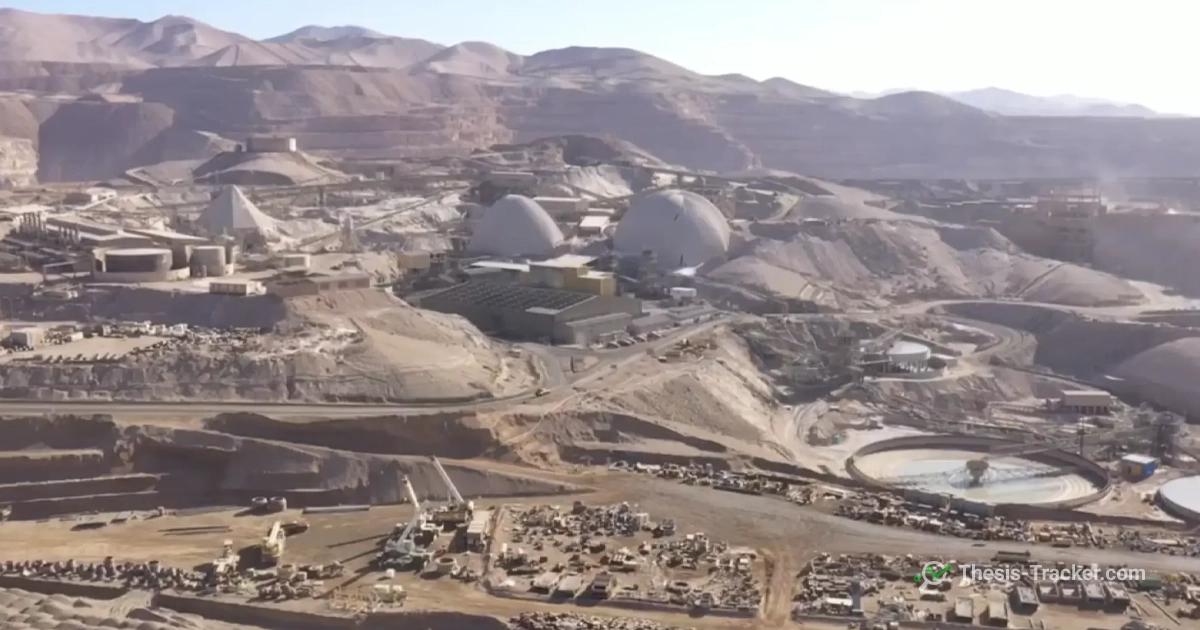
PM Capital's August 2025 Monthly Report detailed the approval of the Mantoverde Optimiser project, a US$170-176 million brownfield expansion that will increase copper throughput by 40% and extend the life of Capstone's highest-quality asset to 25 years, fully funded following a debt refinancing. Antares Capital's own August 2025 report was more cautious, noting Capstone has had a habit of missing production and capital expenditure targets, which sees it trade at a material discount to global copper mining peers despite what it called a better pipeline of volume growth.
Despite this short-term move, the long-term thesis remains intact and tied to structural supply constraints and accelerating demand from the AI data centre and EV sectors.
— PM Capital, Monthly Report, March 2026
That pattern repeated through early 2026. PM Capital's February 2026 Monthly Report detailed 2026 production guidance coming in roughly 10% below consensus, driven by strike-related disruptions and lower grades at the flagship Mantoverde mine, even as a new three-year labour agreement was reached with unions. Ellerston Capital's March 2026 report noted a first-time medium-term CY27 production target of around 265,000 tonnes, also roughly 10% below expectations, compounding an 8% fall in the copper price that month to drive the stock down nearly 30% for the quarter.
What managers are watching next
Despite the volatility, several managers used the weakness to add to positions. PM Capital's March 2026 Quarterly Report detailed increasing its holding following a peak-to-trough decline of 45%, while acknowledging Capstone's asset portfolio is not as strong as some other holdings in the sector but arguing the valuation discount to copper peers is not justified. Pendal Group's May 2026 Newsletter confirmed a subsequent recovery, with group EBITDA beating expectations by 10% to a record US$329 million on higher copper prices and silver by-product credits, with net debt improving by US$43 million to US$738 million.
Questions
Why does Capstone Copper trade at a discount to peers?
Antares Capital notes Capstone Copper has a history of missing production and capital expenditure targets, which has led the market to apply a valuation discount relative to global copper mining peers despite what several managers view as a strong growth pipeline.
What is Capstone Copper's Mantoverde Optimiser project?
The Mantoverde Optimiser is a brownfield expansion project, costing around US$170-176 million, that will increase copper throughput by 40% and extend the life of Capstone Copper's highest-quality asset in Chile to 25 years.
Why do fund managers remain positive on Capstone Copper long term?
PM Capital and Yarra Capital Management point to structural copper demand from electrification, AI data centres and EVs, alongside Capstone's potential to nearly double production by the end of the decade, as reasons for maintaining a positive long-term view despite near-term operational setbacks.
16 managers, 39 comments, with each manager's latest recorded position.
See CSC