

Dalrymple Bay Infrastructure's Income Story Is Backed by Real Earnings Growth
A critical coal terminal with take-or-pay, inflation-linked contracts has become a favoured income stock, avoiding the yield-trap trap as its distribution compresses.
15 Oct 2026 · 3 min read
In short
Dalrymple Bay Infrastructure rose 44% as Brookfield and QIC's exit removed an overhang and unlocked index inclusion for the coal terminal operator's take-or-pay, inflation-linked contracts.
The company holds a lease over the Dalrymple Bay coal terminal until 2051, with an option to extend to 2100, earning inflation-linked pricing from some of the world's best metallurgical coal producers.
Ten Cap notes the distribution yield has compressed from around 7% to about 5%, but argues genuine earnings growth, rather than yield alone, is what makes Dalrymple Bay attractive rather than a value trap.
Dalrymple Bay Infrastructure has emerged as one of the ASX's favoured income stocks, rising 44 percent and beyond as Brookfield and QIC's exit removed an overhang and unlocked index inclusion, with fund managers valuing its take-or-pay, inflation-linked coal terminal contracts that have delivered genuine earnings growth even as the distribution yield has compressed from around 7 percent to about 5 percent.
A newly liquid, increasingly institutional-owned asset
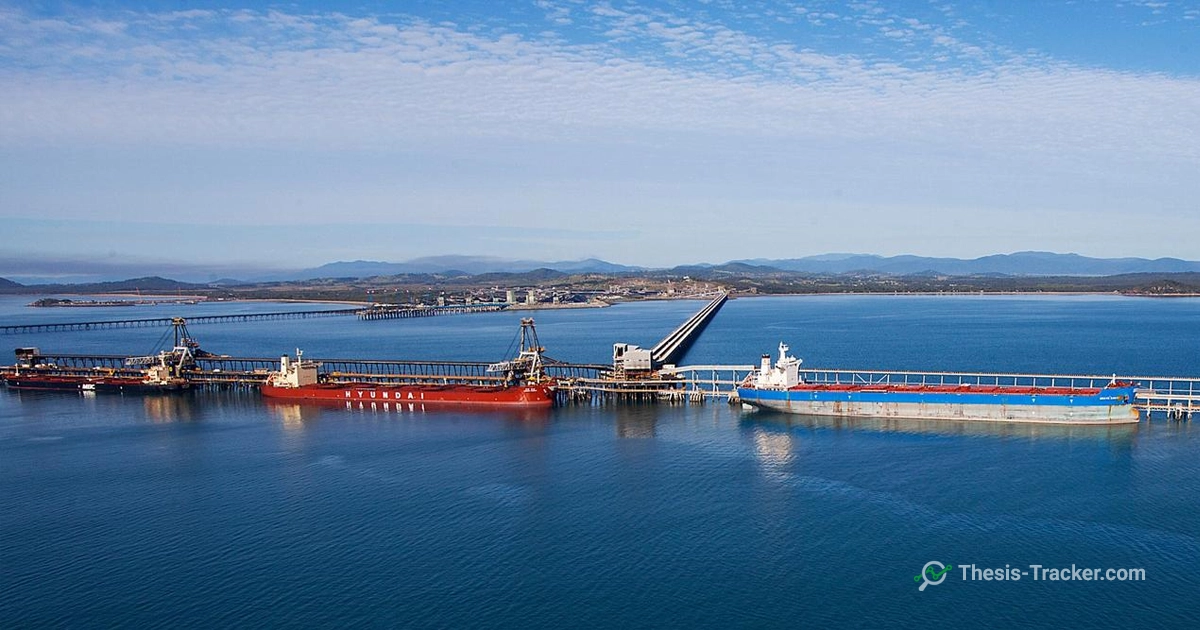
Blackwattle Investment Partners said Dalrymple Bay had not had a long listed life, but was starting to gain more notoriety now that Brookfield and QIC, the groups that brought it to market, had exited, with the stock subsequently entering several indices, describing a coal terminal in Queensland servicing the Bowen Basin that has operated since the mid-1980s, starting life as a 15 million tonne facility. Atlas Funds Management said it added a new position, a coal export terminal with take-or-pay contracts trading on an attractive 6 percent dividend yield, having watched the stock for several months before Brookfield's exit provided an attractive entry point. Contact Asset Management said the high-margin coal terminal showcased solid recent results underpinned by resilient coal export volumes and contractual stability, with effective cost controls and a 95 percent utilisation rate supporting a quarterly distribution of 6.125 cents per stapled security, and the stock up 44 percent over the period.
The results reflect effective cost controls and a 95% utilization rate at the terminal, supporting a quarterly distribution of 6.125 cents per stapled security. DBI has increased by 44% over the period.
— Contact Asset Management, Monthly Report, September 2025
A unique, lightly regulated critical asset
Investors Mutual Limited, naming Dalrymple Bay a guest pick, said it is quite a unique asset, owning critical infrastructure through a lease over the coal terminal running until 2051 with an option to extend to 2100, earning inflation-linked pricing on the coal it distributes for some of the world's best metallurgical coal producers under a light-handed regulatory regime. Market Partners said Dalrymple Bay is exactly the sort of stock it loves for income, having owned it for a number of years, describing critical infrastructure with take-or-pay contracts that continue to ratchet higher each year, with the company recently upgrading FY26 guidance and distributions expected to increase around 8.5 percent for the year.
They've got a lease over the Dalrymple Bay coal terminal until 2051 with an option to extend till 2100. They get inflation linked pricing on the coal that they distribute for some of the best met coal producers in the world.
— Investors Mutual Limited, Article, June 2026
Earnings growth, not just yield, drives conviction
Ten Cap said Dalrymple Bay is a small company many investors haven't paid much attention to, having yielded around 7 percent not that long ago and now back to about 5 percent, but argued the key thing with yield stocks is needing earnings growth, otherwise they become value traps that destroy capital, and Dalrymple Bay actually has very good earnings growth behind it. DS Capital said the company performed well over the year, supported by a highly resilient underlying business and strong distribution growth, providing critical terminal services to the global steelmaking supply chain with capacity fully locked in on take-or-pay arrangements and charges that are inflation-linked, dependable and generating growing cash flows.
Not that long ago it was yielding around 7%. It's now back to about 5%, but one of the key things with yield stocks is that you need earnings growth. Otherwise, they can become value traps and destroy capital. Dalrymple Bay actually has very good earnings growth.
— Ten Cap, Article, June 2026
What fund managers say they are watching next is continued expansion of terminal capacity beyond its original 15 million tonnes, delivery of the roughly 8.5 percent FY26 distribution growth guidance, whether earnings growth continues supporting the yield as it compresses further, and progress toward securing the long-dated lease extension option to 2100.
Questions
Why did Dalrymple Bay Infrastructure's share price rise so strongly?
Dalrymple Bay Infrastructure rose 44% as original owners Brookfield and QIC exited, removing an overhang and enabling the stock to enter several indices, while its take-or-pay, inflation-linked coal terminal contracts continued delivering resilient earnings.
How long is Dalrymple Bay Infrastructure's lease over its coal terminal?
Dalrymple Bay Infrastructure holds a lease over the coal terminal until 2051, with an option to extend to 2100, earning inflation-linked pricing on coal distributed for some of the world's best metallurgical coal producers.
Why do fund managers say Dalrymple Bay Infrastructure isn't a yield trap?
Ten Cap argues that unlike many high-yield stocks, Dalrymple Bay Infrastructure has genuine earnings growth behind it, which is why the stock has performed well even as its distribution yield compressed from around 7% to about 5%.
17 managers, 31 comments, with each manager's latest recorded position.
See DBI