

Jupiter Mines' takeover optionality builds after Exxaro's stake in a key partner
A corporate takeover involving one of Jupiter Mines' Tshipi joint venture partners has left African miner Exxaro holding a 20% stake in the company, creating a takeover optionality case that fund managers see as compelling given the yield on offer while waiting.
8 Apr 2026 · 3 min read
In short
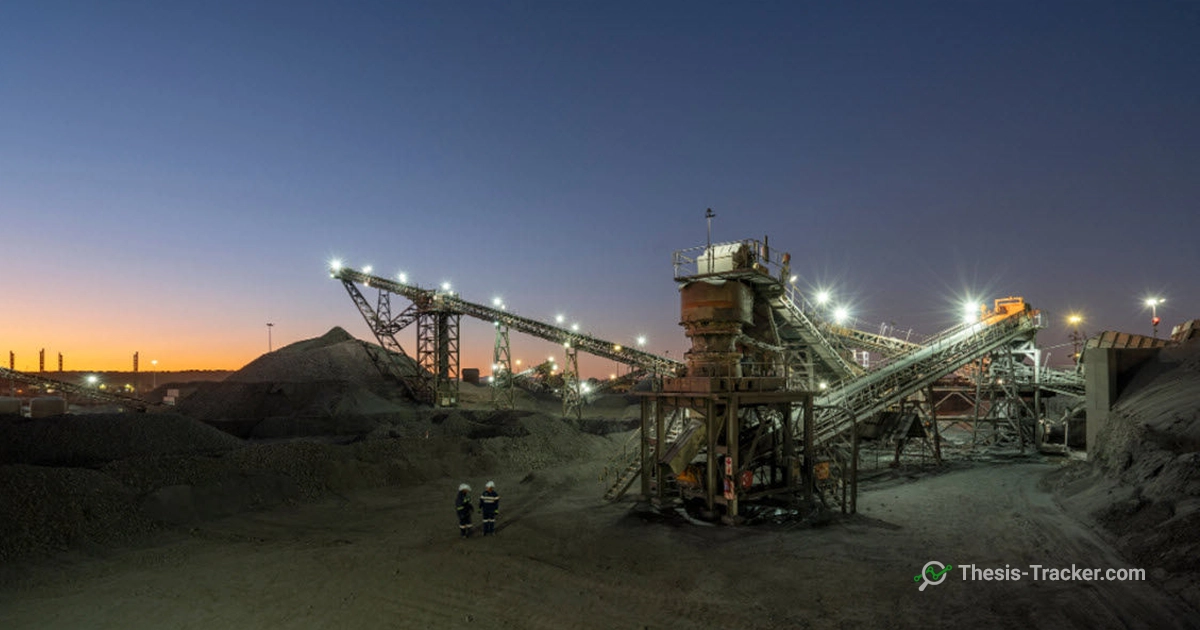
Jupiter Mines owns just under 50% of the world-class Tshipi manganese mine in South Africa, which Lanyon Investment Fund notes has a mine life of more than 100 years and sits next to South32's Mamatwan Mine.
African miner Exxaro's takeover of a Jupiter Mines partner has left Exxaro holding an effective 20% shareholding in Jupiter plus a large interest in the Tshipi Mine itself, a transaction Datt Capital says implies a valuation of around 33 cents per Jupiter share against a market price of 28 cents.
Datt Capital likes Jupiter Mines as a pragmatic, safe pick given shareholders are paid a dividend yield of around 5-6% while waiting for the takeover optionality it believes will eventually play out.
Jupiter Mines Ltd (ASX: JMS) owns a stake in one of the world's premier manganese assets, and a corporate transaction involving one of its joint venture partners has since created a genuine takeover optionality case that several fund managers find compelling. Lanyon Investment Fund explained its initial purchase in September 2025, noting Jupiter owns one of the largest producing manganese mines in the world with a mine life of more than 100 years, and that it expected further corporate activity involving the company's largest shareholder.
A partner's takeover creates an unusual ownership structure
Datt Capital detailed the mechanics of that corporate activity in April 2026, explaining Jupiter owns just under 50% of the world-class Tshipi Mine in South Africa, sitting next to South32's large Mamatwan Mine. Roughly a year prior, large African miner Exxaro took over one of Jupiter's joint venture partners, a transaction that resulted in Exxaro holding an effective 20% shareholding in Jupiter itself, plus a large direct interest in the Tshipi Mine asset. Datt Capital described this as leaving Jupiter in an unusual position, caught between a rock and a hard place given Exxaro's dual exposure both to Jupiter's equity and to the underlying mine.
The implied price for this transaction by Exxaro implied a valuation of about 33 cents per Jupiter share. Market price is about 28 today. I think it's a really interesting asset because shareholders are being paid a fairly decent yield of about 5-6% with that takeover optionality that I believe will happen in time.
Datt Capital, Article, April 2026
A tactical exit alongside continuing believers
Not every fund manager has stayed the course. NGE Capital reported exiting its Jupiter Mines holding in October 2025, netting approximately $1 million in profit including dividends received, a realised gain that suggests the position had already performed well before the exit. Datt Capital, by contrast, continued to view the stock as a pragmatic, safe pick specifically because of the combination of a solid dividend yield and the takeover optionality it expects to eventually materialise given Exxaro's stake.
What managers are watching next
With the Exxaro transaction implying a valuation of around 33 cents per Jupiter share against a market price of roughly 28 cents, the catalysts fund managers are tracking are whether Exxaro moves to consolidate its position further given its dual exposure to both Jupiter's equity and the Tshipi Mine asset, and whether the 5-6% dividend yield continues to compensate holders adequately while that takeover optionality plays out.
Questions
What is Jupiter Mines' key asset?
Jupiter Mines owns just under 50% of the world-class Tshipi manganese mine in South Africa, which Lanyon Investment Fund notes has a mine life of more than 100 years and sits adjacent to South32's large Mamatwan Mine.
Why does Exxaro's stake in Jupiter Mines matter?
African miner Exxaro's takeover of a Jupiter Mines joint venture partner left it holding an effective 20% shareholding in Jupiter plus a large interest in the Tshipi Mine itself, a transaction Datt Capital says implied a valuation of around 33 cents per Jupiter share against a market price of roughly 28 cents.
Why does Datt Capital call Jupiter Mines a pragmatic, safe pick?
Datt Capital likes Jupiter Mines because shareholders are paid a dividend yield of around 5-6% while waiting for the takeover optionality created by Exxaro's stake, which the fund believes will eventually play out.
6 managers, 9 comments, with each manager's latest recorded position.
See JMS