

Why fund managers exited Meeka Metals after a promising mine restart
Meeka Metals commissioned a restarted gold mine with resource upgrade and plant expansion potential, but a rainfall event and guidance downgrade prompted several managers to sell.
26 Jun 2026 · 4 min read
In short
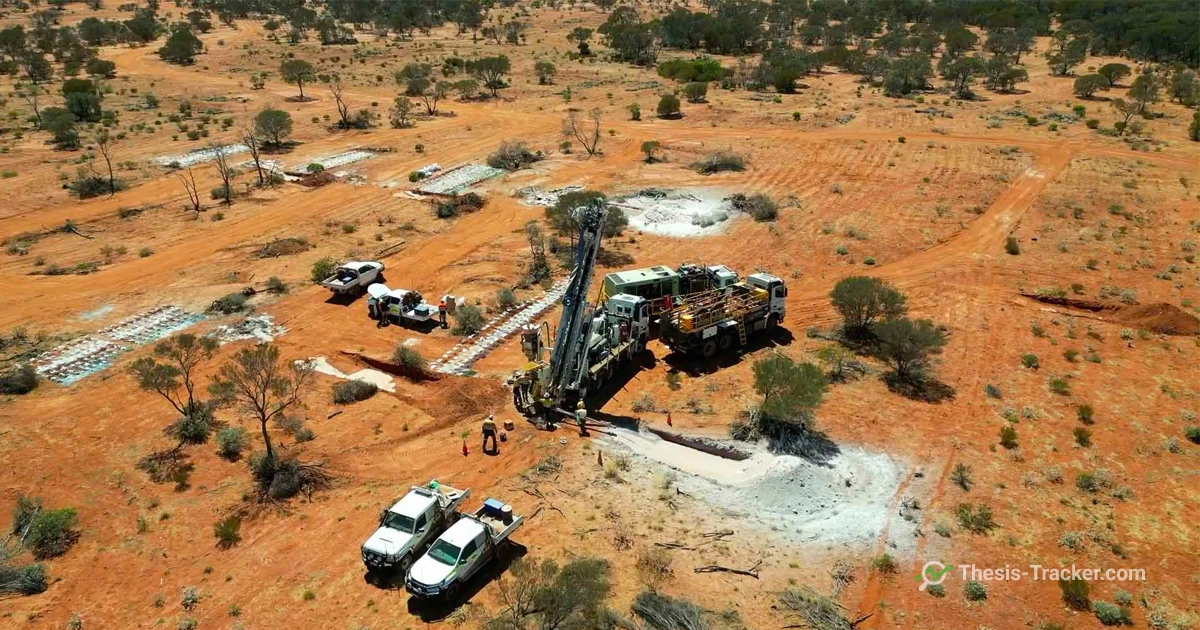
Meeka Metals commissioned the restart of an old gold mine in late 2025, with potential resource upgrades and a plant expansion that could double production.
Oracle Advisory Group significantly increased its position in the December 2025 quarter, with the stock rising 87% since initial purchase.
Ellerston Capital and Acorn Capital both exited their positions in 2026 after a rainfall event forced a production guidance downgrade.
Gold developer Meeka Metals commissioned a restart of an old gold mine in late 2025, and Maple-Brown Abbott's October 2025 Article flagged two specific sources of unpriced upside: conservative geological resource estimates suggesting more gold in the ground than currently modelled, and a logical plant expansion project that could potentially double production over the next few years.
A promising ramp-up interrupted by weather and operational issues
Maple-Brown Abbott's report argued that absent any change in the gold price, the stock could still double over the next few years purely on the combination of resource upgrades and the plant expansion opportunity, once the usual commissioning ramp-up issues were worked through with what it viewed as a strong management team. Oracle Advisory Group's December 2025 Quarterly Report confirmed early momentum, having significantly increased its position at the start of the December quarter, with the fund's three gold miners becoming its three largest positions after Meeka rose 87% since initial purchase.
There is a risk the company needs to raise money if performance is poor in the June quarter. However, if management can turn things around, the company is currently looking attractive compared to its peers.
— Acorn Capital, Article, June 2026
The ramp-up proved rockier than hoped. Ellerston Capital's April 2026 Monthly Report detailed the stock falling 20% despite a broader gold price recovery that month, after the company downgraded production guidance following a significant rainfall event during the quarter, prompting Ellerston to exit its position. Acorn Capital's June 2026 Article confirmed it had also exited after operational issues during ramp-up, though it kept the stock on its watchlist given the mine's location in a geologically prospective region and continued confidence in management.
What managers are watching next
Seneca Financial Solutions' May 2026 Article used Meeka as a peer comparison for valuing other small gold producers, noting the roughly 50,000-ounce-per-annum producer carried a $400 million market capitalisation at the time. With Acorn Capital flagging a risk the company may need to raise capital if June quarter performance disappoints, the near-term operational update remains the key document managers who exited are waiting on before reconsidering the stock.
Questions
What upside did fund managers see in Meeka Metals?
Maple-Brown Abbott identified two sources of unpriced upside: conservative geological resource estimates suggesting more gold in the ground than currently modelled, and a plant expansion project that could potentially double production over the next few years.
Why did fund managers exit Meeka Metals?
Ellerston Capital and Acorn Capital both exited their positions after the company downgraded production guidance following a significant rainfall event during the quarter, which hit the share price despite a broader gold price recovery.
Is there risk Meeka Metals will need to raise capital?
Acorn Capital flags a risk that Meeka Metals may need to raise money if performance in the June quarter is poor, though it remains on the manager's watchlist given the mine's location in a geologically prospective region.
7 managers, 8 comments, with each manager's latest recorded position.
See MEK