

Why fund managers see Metro Mining's cash flow potential as underappreciated
Metro Mining's bauxite operations keep generating strong cash flow potential, but production hiccups and Guinea supply news continue to drive sharp share price swings.
30 Jun 2026 · 5 min read
In short
Metro Mining could generate roughly A$200 million in operating cash flow at steady-state 7.5 million tonnes per annum shipping, against a market cap of only around A$400 million, according to Paradice Investment Management.
Guinea, which produces around 75% of the world's seaborne bauxite, has repeatedly driven Metro Mining's share price with news of planned production limits.
DMX Asset Management reduced its position from a high of around 7% of the portfolio to around 4% following a 23% share price fall driven by production hiccups.
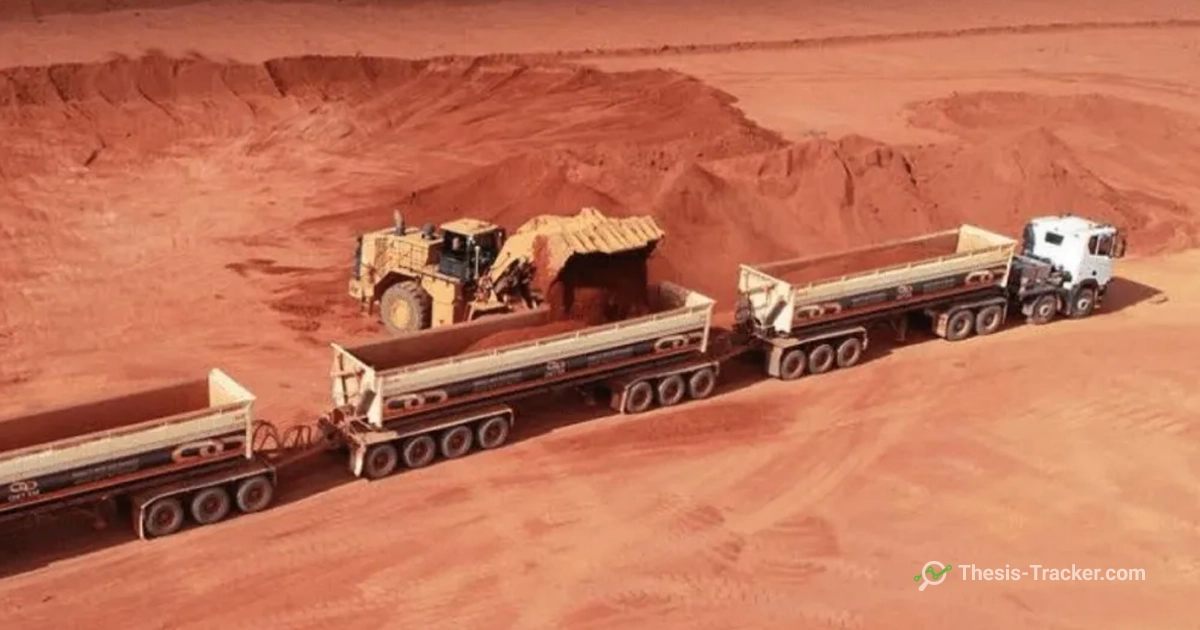
Bauxite producer Metro Mining operates what Firetrail Investments' September 2025 Monthly Report described as a unique small-cap combination: exposure to structurally growing aluminium demand, a low-cost position relative to peers, a long and expandable mine life, and high free cash flow generation, with the manager anticipating quarterly free cash flow of around $40 million and an underlying free cash flow yield of over 20% at the time.
Operational hiccups against a supportive bauxite market
Paradice Investment Management's December 2025 Monthly Report detailed a quarter where strong operational results, including record shipments of 2.25 million tonnes and multiple production milestones, were overshadowed by weaker realised pricing and lower-than-expected cash flow, with CY25 guidance trimmed to 6.2-6.6 million tonnes due to weather-related constraints and a temporary barge loader failure at Skardon River. The report modelled the company's steady-state potential once legacy contracts rolled off: at 7.5 million tonnes per annum of shipping and a cash margin of A$25-30 per tonne, Metro Mining could generate roughly A$200 million in operating cash flow, against a market capitalisation of only around A$400 million at the time.
With Guinea — which accounts for around 75% of Asia Pacific bauxite supply — experiencing production disruptions, the broader commodity backdrop remains supportive.
— Paradice Investment Management, Monthly Report, December 2025
That Guinea supply dynamic proved to be a recurring catalyst through 2026. Perennial Partners' May 2026 Monthly Report detailed the stock bouncing 17.5% after Guinea, which produces around 75% of the world's seaborne bauxite, announced plans to limit production from the country, with a further 17.9% bounce in June on similar reports of impending Guinean production cuts. Perennial's June 2026 report also confirmed an operational recovery domestically, with May shipments of 604,000 tonnes up 45% on the prior month following the return of the Offshore Floating Terminal Ikamba and restoration of full transhipment capacity, alongside maintained CY26 shipment guidance of 6.6-7.1 million tonnes weighted to the second half.
What managers are watching next
DMX Asset Management's October 2025 Monthly Report detailed materially reducing its position from a high of around 7% of the portfolio back to around 4% following a 23% share price fall driven by production hiccups and reduced volume and margin expectations, while remaining comfortable with continued exposure given contained downside and potential for meaningful contribution if the story plays out as anticipated. With Maple-Brown Abbott's March 2026 Quarterly Report noting management has redesigned safety incentives to encourage more thorough near-miss reporting, and Guinea's ongoing production discipline supporting the broader bauxite price backdrop, managers are watching whether Metro Mining's operational reliability can finally catch up with the underlying cash generation potential of the asset.
Questions
Why is Guinea important to Metro Mining's share price?
Guinea produces around 75% of the world's seaborne bauxite, and news of planned production limits from the country has repeatedly driven sharp rallies in Metro Mining's share price given the resulting support for global bauxite prices.
What is Metro Mining's cash flow potential?
Paradice Investment Management estimates Metro Mining could generate roughly A$200 million in operating cash flow at steady-state shipping of 7.5 million tonnes per annum and a cash margin of A$25-30 per tonne, against a market capitalisation of only around A$400 million.
Why has Metro Mining's share price been volatile?
DMX Asset Management notes the stock has swung sharply on production hiccups, including weather-related constraints and equipment failures at its Skardon River operations, alongside recurring news about Guinea's bauxite production plans.
7 managers, 11 comments, with each manager's latest recorded position.
See MMI