

Paladin Energy's Nuclear Thematic Meets a Track Record of Downgrades
Rising uranium prices and strong operations at Langer Heinrich support the bull case, but a history of downgrades and Canadian project resistance have two fund managers saying sell.
3 Jul 2026 · 3 min read
In short
Paladin Energy serves as a key nuclear demand thematic exposure for fund managers, benefiting from spot uranium prices rising 23% to US$100 a pound and strong operational performance at its Langer Heinrich mine in Namibia.
Alphinity Investment Management and Maple-Brown Abbott independently arrived at sell ratings, citing a history of operational downgrades and expectations for FY27 production and unit costs that remain too high.
Paladin Energy's Patterson Lake South project in Saskatchewan, Canada, received Ministerial EIS approval, but is meeting significant community resistance according to Alphinity Investment Management.
Paladin Energy, a key exposure to the nuclear demand thematic driven by AI-related data centre power needs, rallied on rising spot uranium prices and strong operational performance at its Langer Heinrich mine, before a history of operational downgrades and community resistance to its Canadian Patterson Lake South project led two fund managers to independently arrive at the same sell rating.
A key nuclear demand thematic exposure
Blackwattle Investment Partners said Paladin is the fund's key exposure to the nuclear demand thematic given the world's need for baseload power to support a growing fleet of intermittent renewable generators, with the uranium producer well positioned to benefit from near-term high incentive pricing required to stimulate further uranium production, making the uranium price outlook a key driver of the stock. Yarra Capital Management, underweight, said the uranium producer outperformed in January on higher commodity prices, with spot uranium prices increasing 23 percent across the month to close at US$100 a pound, and while the company's production is largely contracted, spot prices remain an important influence on earnings and the medium-term outlook.
Paladin Energy is the fund's key exposure to the nuclear demand thematic with the world's need for baseload power to support a growing fleet of intermittent renewable generators. As a uranium producer, Paladin is well-positioned to benefit from the near-term high incentive pricing required to stimulate further uranium production.
— Blackwattle Investment Partners, Monthly Report, November 2025
Strong operations, expanding project pipeline
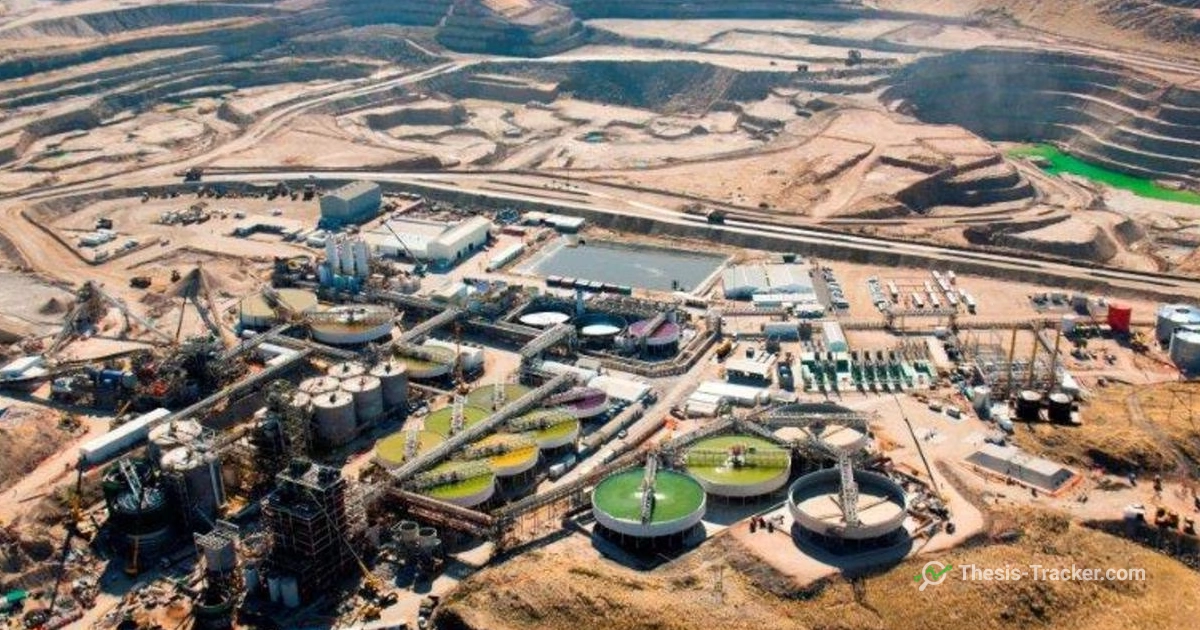
Oracle Advisory Group said Paladin's exposure to uranium, which it believes will be in high demand due to exponential growth in power needs from data centres, includes a currently producing mine in Africa and a project in Canada. Acorn Capital said the stock rose 15.40 percent after announcing strong operational performance in the December quarter at the Langer Heinrich mine in Namibia, up 16 percent quarter on quarter, alongside receiving Ministerial EIS approval for the Patterson Lake South project in Saskatchewan, Canada.
Paladin Energy announced strong operational performance in the December quarter at their Langer Heinrich mine in Namibia (up 16% quarter-on-quarter). They also received Ministerial EIS approval for their Patterson Lake South project in Saskatchewan, Canada.
— Acorn Capital, Quarterly Report, March 2026
Two independent sell ratings converge
Alphinity Investment Management's Andre rated the stock a sell, saying he likes uranium as a commodity but the company has had quite a lot of operational downgrades over the years, believing expectations for FY27 are still too high from both a production and unit cost perspective, with the Patterson Lake project in Canada meeting quite a lot of community resistance. Maple-Brown Abbott's Dougal Maple-Brown agreed with almost everything said, also rating the stock a sell, acknowledging that in fairness to Paladin it is investible, unlike some companies in the sector, and it is producing and profitable, ticking the basic boxes, but not enough to get there.
Sell. Uranium is a commodity that we like. However, the company has had quite a lot of operational downgrades over the years. We think that the expectations for FY27 are still too high from a production perspective and also from a unit cost perspective. The Patterson Lake project in Canada is meeting quite a lot of resistance.
— Alphinity Investment Management, Article, July 2026
What fund managers say they are watching next is whether FY27 production and unit cost guidance proves achievable given the history of downgrades, resolution of community resistance to the Patterson Lake South project in Canada, continued spot uranium price momentum tied to data centre power demand, and whether Langer Heinrich's operational performance continues improving.
Questions
Why is Paladin Energy considered a key nuclear demand thematic exposure?
Blackwattle Investment Partners describes Paladin Energy as a key exposure to the nuclear demand thematic given the world's need for baseload power to support a growing fleet of intermittent renewable generators, benefiting from rising uranium incentive pricing.
Why do fund managers rate Paladin Energy a sell despite liking uranium?
Alphinity Investment Management and Maple-Brown Abbott both rate Paladin Energy a sell, citing a history of operational downgrades and viewing FY27 production and unit cost expectations as still too high.
What resistance is Paladin Energy's Patterson Lake South project facing?
Despite receiving Ministerial EIS approval, Paladin Energy's Patterson Lake South project in Saskatchewan, Canada, is meeting quite a lot of community resistance, according to Alphinity Investment Management.
8 managers, 21 comments, with each manager's latest recorded position.
See PDN