

Peter Warren Automotive Seen as a Cheap Play on Falling Rates
Fund managers say the car dealer group is a later-cycle beneficiary trading well below larger rival AP Eagers
4 Jun 2026 · 3 min read
In short
Wilson Asset Management says falling interest rates have turned Australia's auto dealer cycle, benefiting Peter Warren Automotive.
1851 Capital notes Peter Warren trades on 13 times earnings versus 25 times for larger rival AP Eagers.
Hayborough Investment Partners says the current share price is below the value of the company's own land holdings.
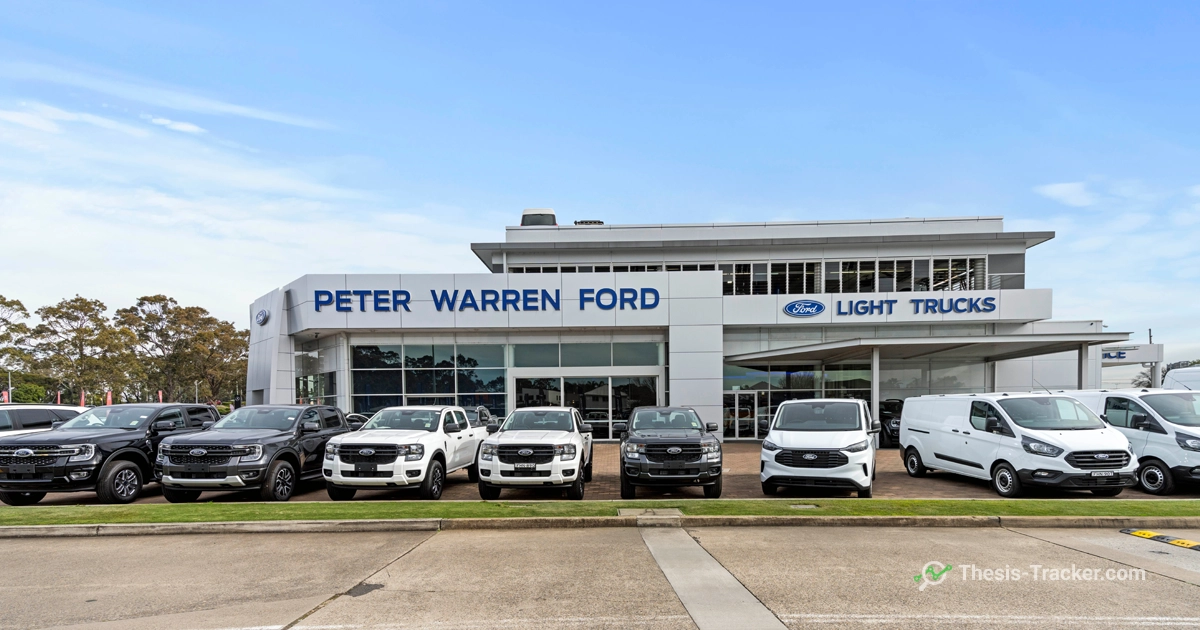
As Australia's auto dealer cycle turns, fund managers are increasingly framing Peter Warren Automotive as a later-cycle beneficiary of falling interest rates, trading at a wide discount to larger rival AP Eagers despite similar tailwinds.
A cheaper way to play the same interest rate tailwind
Wilson Asset Management's Sam Koch made the comparison directly in August 2025, tipping that Peter Warren, then down 40 per cent since September 2022, would follow the rally already enjoyed by AP Eagers, whose share price had doubled over the prior year as rates fell.
The auto dealer cycle has decisively turned. Three interest rate cuts this year have already lowered inventory holding costs and ignited consumer demand, with any further cuts set to accelerate these gains.
— Wilson Asset Management, Article, August 2025
A mortgage belt customer base turns into a tailwind
1851 Capital's November 2025 commentary sharpened the valuation gap: AP Eagers had become the most expensive car dealer globally on a 25 times earnings multiple after more than doubling, while Peter Warren traded on just 13 times. The manager pointed to the company's customer base, concentrated in the mortgage belt, as a source of headwinds during the rate-hiking cycle that was now turning into a tailwind as rates fall, alongside a growing push into Chinese electric vehicle brands taking market share.
By June 2026, Hayborough Investment Partners was building a position after a further share price fall, arguing the stock traded well below the value of its own property holdings, so that the underlying car dealership business was effectively being acquired for free. Hayborough pointed to the company's 65-year operating history and ownership by three of Australia's most experienced car retailing families as reasons for patience, while acknowledging the cycle's bottom may not yet be in.
Questions
Why do fund managers see Peter Warren Automotive as a beneficiary of falling interest rates?
Wilson Asset Management said three interest rate cuts had already lowered inventory holding costs and lifted consumer demand for car dealers, with 1851 Capital adding that Peter Warren's mortgage-belt customer base turns rate cuts into a particular tailwind for the business.
How does Peter Warren Automotive's valuation compare with AP Eagers?
1851 Capital noted in November 2025 that AP Eagers traded on 25 times earnings after more than doubling in a year, while Peter Warren traded at just 13 times, despite facing similar industry tailwinds.
Why did Hayborough Investment Partners buy Peter Warren Automotive?
Hayborough Investment Partners said in June 2026 that the share price had fallen below the value of the company's own land holdings, meaning investors were effectively getting the car dealership business for free.
4 managers, 4 comments, with each manager's latest recorded position.
See PWR