

Rox Resources Nears Production at Youanmi as Broker Targets Run Ahead
Fund managers say the high-grade project remains undervalued against peers, though a royalty overhang complicates financing
18 May 2026 · 4 min read
In short
Rox Resources' Youanmi project targets up to 140,000oz of gold per annum, with first gold expected within 18 months.
Broker price targets of $1.06 to $1.15 sit well above Rox's ~50 cent share price, Seneca Financial Solutions says.
A third-party royalty over Youanmi remains an unresolved overhang complicating Rox's debt financing options.
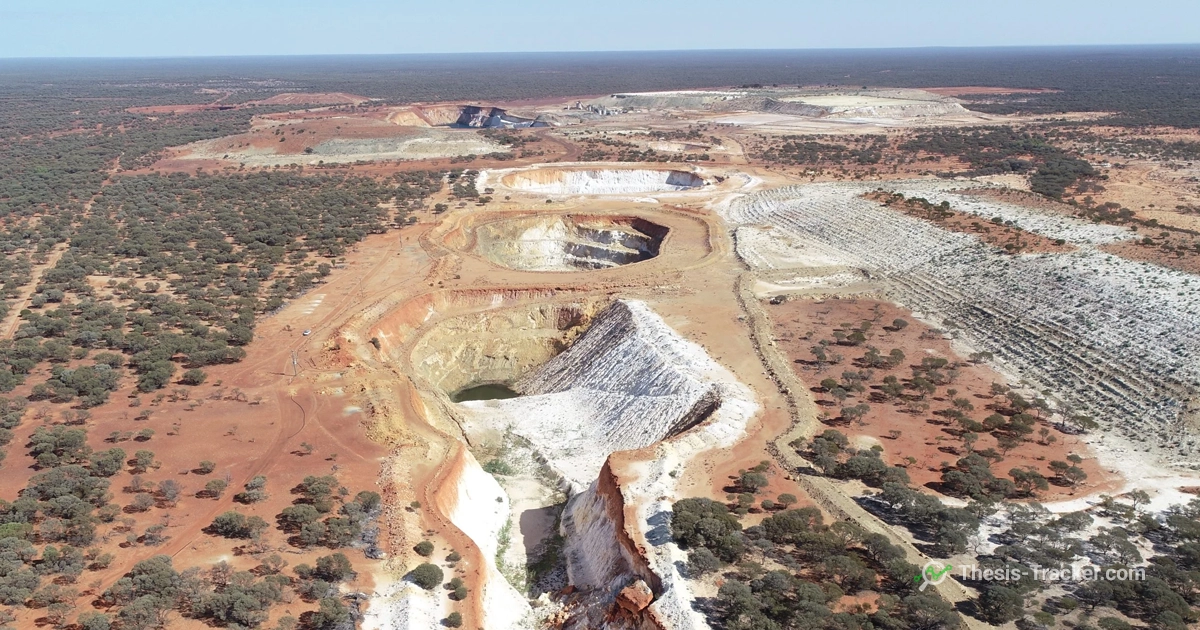
Developer of the high-grade Youanmi gold project in Western Australia, Rox Resources has drawn fund manager support on a well-funded path to production, even as broader gold sector volatility and a lingering royalty dispute complicate the picture.
A well-funded, high-grade project with re-rating room
Blackwattle Investment Partners' December 2025 update described Rox rising 19.3 per cent as investor confidence built around the company's transition toward production, helped by a well-received capital raise at 35 cents that strengthened the balance sheet. Youanmi is a high-grade underground gold system, with jumbo development underway and first gold targeted in under 18 months, and a Definitive Feasibility Study outlining potential production of up to 140,000 ounces per annum.
Despite the recent rally we believe Rox continues to offer significant upside as it progresses toward production, with its market cap of approximately $700m still well below ASX Small Ordinaries peers producing +100koz per annum, who typically trade above $2bn.
— Blackwattle Investment Partners, Monthly Report, January 2026
Broker targets well above the current share price
Seneca Financial Solutions' February 2026 update noted Rox had become the highest-grade standalone gold developer in Australia following Ramelius Resources' acquisition of Spartan, with broker price targets ranging from $1.06 to $1.15, against a share price of around 52 cents at the time. Seneca expected Rox to rally toward its net present value as it de-risked to production, pointing to strategic proximity to Ramelius' Penny gold mine and Mt Magnet mill, and to a chunky $218 million equity raise late in 2025 that left the project well funded.
Sector-wide weakness, then renewed drilling upside
Not all of the volatility has been company-specific. Perennial Partners reported Rox fell 21.7 per cent in March 2026, reflecting broad-based pressure across the gold sector as bullion itself fell 11.6 per cent that month. Seneca Financial Solutions' subsequent commentary in May 2026 pointed to fresh drilling results, including intersections of 5 metres at 14 grams per tonne gold outside the current mine plan, arguing the project's true resource potential looked like the tip of the iceberg given many underground mines run reserve lives well beyond 10 years.
An unresolved royalty overhang
Seneca's commentary also flagged a complicating factor: a third-party royalty over the project that makes debt financing more expensive, and an unresolved situation involving major shareholder QGold's offer for a stake in the royalty holder. Seneca suggested Rox had not yet moved to acquire the royalty itself because it was waiting for QGold's proposal to lapse, wary of antagonising a significant shareholder by engaging a competing bid while that offer remained live, an overhang investors continue to watch alongside the project's construction progress.
Questions
What production is Rox Resources targeting at Youanmi?
Blackwattle Investment Partners reported that Rox Resources' Definitive Feasibility Study for its Youanmi project outlines potential production of up to 140,000 ounces of gold per annum, with first gold targeted within 18 months as of early 2026.
How does Rox Resources' valuation compare with broker price targets?
Seneca Financial Solutions reported broker price targets of $1.06 to $1.15 for Rox Resources in February 2026, against a share price of around 52 cents at the time, expecting the stock to rally toward its net present value as it de-risks toward production.
What royalty issue affects Rox Resources' Youanmi project?
Seneca Financial Solutions said a third-party royalty over the Youanmi project makes debt financing more expensive, and that Rox appeared to be waiting for a rival shareholder's offer for the royalty holder to lapse before making its own move to acquire the royalty.
4 managers, 8 comments, with each manager's latest recorded position.
See RXL