

Scentre Group Adds a Debt Restructure to Its Defensive Income Case
Fund managers say a redemption of expensive 2030 notes adds a fresh earnings tailwind on top of steady Westfield leasing momentum
31 May 2026 · 3 min read
In short
Scentre Group's centres run above 99% occupancy, with total centre sales up 5% and leasing spreads positive at 3.3% in early 2026.
A May 2026 debt restructure redeeming A$1.8 billion of 2030 notes cuts Scentre's blended funding margin by 100 basis points, Pendal says.
Oracle Advisory Group and Antares Capital both added the stock as a defensive, income-generating position benefiting from rising rates.
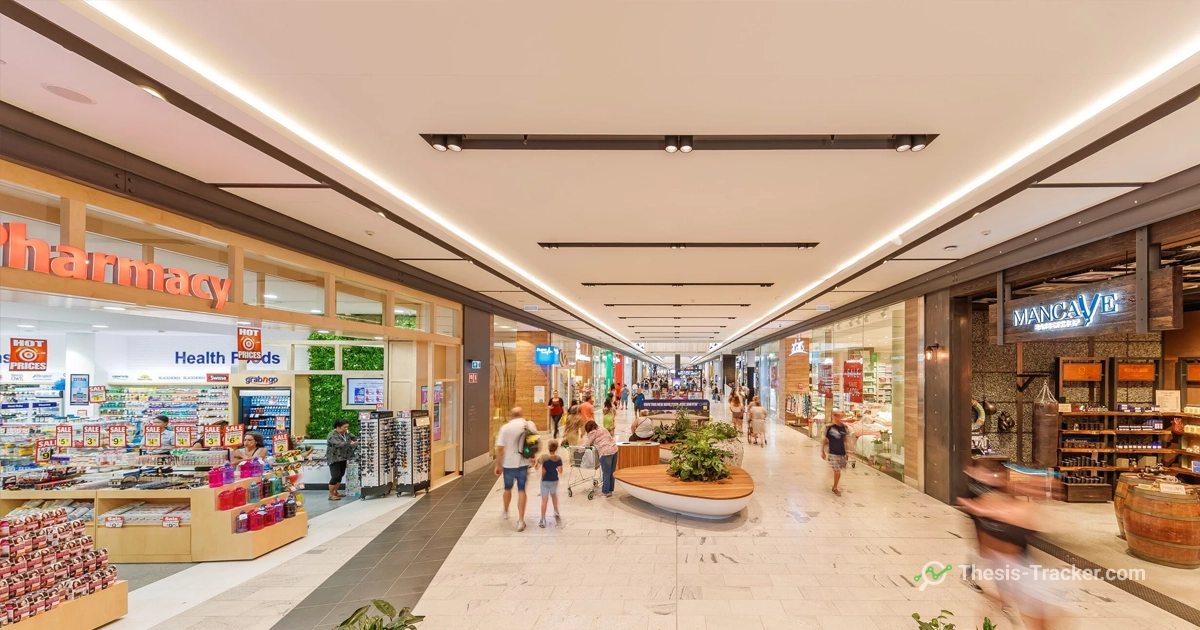
As Australia's largest owner and manager of Westfield shopping centres, Scentre Group has drawn fund managers looking for defensive income, before a debt restructure in 2026 added a fresh earnings tailwind on top of steady rental growth.
A defensive, near-fully-let portfolio
Antares Capital's rationale for adding Scentre in August 2025 centred on balance and optionality: occupancy above 99 per cent, no major shopping centre development underway nationally, and improving retail sales giving the group leverage in negotiations with retailers. Oracle Advisory Group added the stock in December 2025 for similar reasons, framing it as a defensive holding likely to benefit in a rising rate environment and valuing the steady, reliable income that comes with being the country's largest Westfield owner-operator.
Infinity Asset Management's October 2025 update showed the original thesis largely playing out, noting the fund had reduced its position as higher occupancy, positive re-leasing spreads and inflation-linked specialty rental escalations, the pillars of its original case, had already been substantially realised.
Leasing momentum holds through early 2026
Pendal Group's read on the April 2026 first-quarter update showed the operating momentum continuing: total centre sales up 5 per cent, specialty sales up 5.3 per cent, leasing spreads still positive at 3.3 per cent, and average specialty rent escalation of 5.3 per cent, driven by CPI-linked and fixed increases. FY26 guidance for both funds from operations and dividend per share was unchanged at 4 per cent growth.
Scentre Group's 1Q26 update showed strong operational performance with total centre sales +5%, specialty sales +5.3% and that leasing spreads continue to be positive (+3.3%). Average specialty rent escalation was +5.3% driven by CP-linked and fixed increases.
— Pendal Group, Newsletter, April 2026
A debt restructure adds a fresh tailwind
The bigger development came a month later. Pendal Group's May 2026 commentary detailed a debt restructure that materially boosts earnings for the next few years: Scentre will redeem A$1.8 billion of expensive 2030 subordinated notes, using some of the resulting interest savings to improve hedging coverage for FY27 to FY29, effectively pushing part of the FY26 earnings uplift into future periods. Pendal described the 100 basis point reduction in the group's blended funding margin as a meaningful earnings tailwind, alongside extended hedging coverage into 2027-28 that provides protection against rate volatility.
Tamim Funds Management's own May 2026 update tied the operational picture back to the retail environment underpinning it, noting leasing conditions across premium shopping centres remained healthy and tenant sales continued to improve, leaving the business well positioned to benefit from resilient consumer traffic and stable rental collections.
Questions
What debt restructure has Scentre Group undertaken?
Pendal Group reported that Scentre Group is redeeming A$1.8 billion of expensive 2030 subordinated notes, using part of the resulting interest savings to extend hedging coverage into FY27-29, which reduces its blended funding margin by around 100 basis points.
How is Scentre Group's leasing performance tracking in 2026?
Pendal Group's April 2026 update showed total centre sales up 5%, specialty sales up 5.3%, and leasing spreads still positive at 3.3%, with average specialty rent escalation of 5.3% for the first quarter of 2026.
Why did fund managers see Scentre Group as a defensive holding?
Oracle Advisory Group and Antares Capital both cited Scentre Group's over 99% occupancy, its position as Australia's largest owner-manager of Westfield centres, and its steady, reliable income as reasons to hold it for defensive exposure in a rising rate environment.
5 managers, 12 comments, with each manager's latest recorded position.
See SCG