

Stanmore Resources' Coal Discipline Pays Off as the Cycle Finally Turns
Operational consistency through a brutal downturn, a removed capital raise overhang, and a recovering steelmaking coal market have fund managers pointing to a stock trading under 5 times earnings.
31 Aug 2026 · 3 min read
In short
Stanmore Resources maintained positive free cash flow and operational consistency through a two-year steelmaking coal price downturn that forced peers to idle assets and defer capital expenditure.
The stock rose 19% after Anglo American's Queensland steelmaking coal assets were sold to an alternate bidder, removing a potential capital raise overhang and validating management's decision to pass on the deal.
Fund managers including PM Capital note Stanmore now trades under 5 times earnings at spot coal prices as the sector emerges from its two-year downturn, helped by European steelmakers restarting.
Stanmore Resources delivered operational consistency and disciplined cost management through a two-year steelmaking coal price downturn that forced peers into cutbacks, rewarding shareholders with a dividend and steady gains, before management's decision to pass on Anglo American's Queensland coal assets removed a capital raise overhang and confirmed the coal cycle was finally turning.
Resilience through a brutal downturn
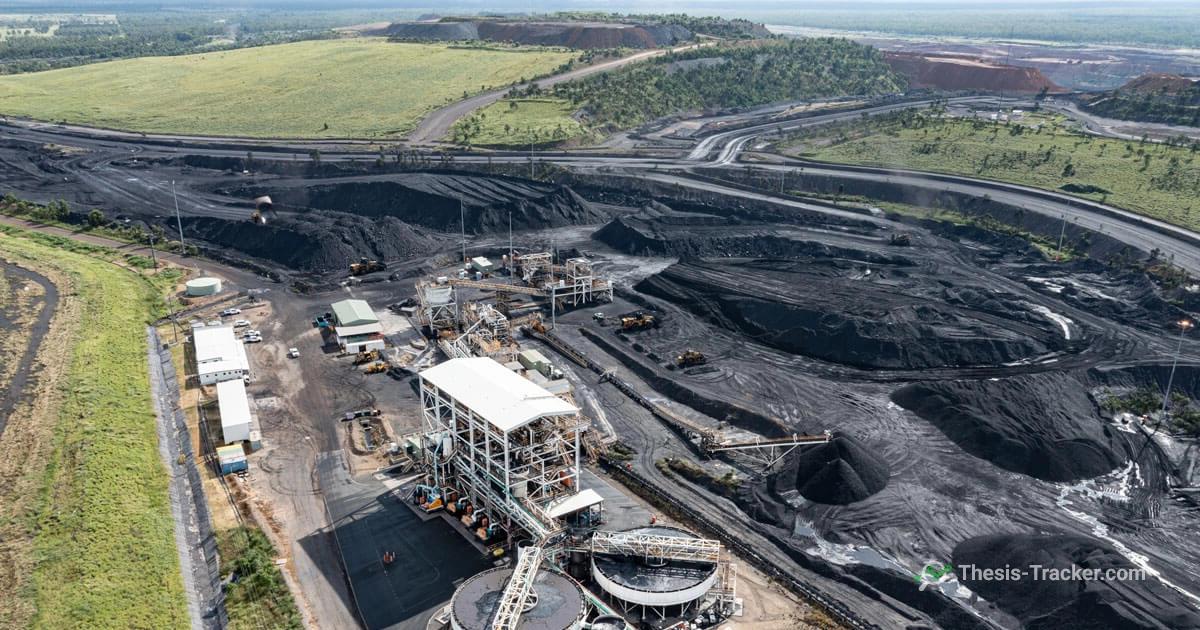
PM Capital said Stanmore remained resilient despite low commodity prices that saw peers, including several industry giants, take measures to preserve cash, including idling underperforming assets, deferring capital expenditure or high-grading their mines to cherry-pick the best reserves. The stock rose 30 percent in January as its fourth-quarter production report highlighted operational consistency that had been critical to maintaining positive cash flow throughout the downturn, with the cycle turning and benchmark coal prices moving higher. Blackwattle Investment Partners said the stock rose 29.7 percent, describing Stanmore as a metallurgical coal producer with diversified production across three mines in Queensland's Bowen Basin, with a reputation for very reliable operating metrics driven by a high-quality management team, even as metallurgical coal had remained relatively depressed until recently.
Stanmore's fourth quarter production report highlighted its operational consistency, which has been critical to maintaining positive cash flow throughout the downturn in coal prices.
— PM Capital, Monthly Report, January 2026
A low-cycle, cheap-valuation opportunity
PM Capital said Middle East LNG supply disruption to Asia supported thermal coal markets and indirectly steelmaking coal markets, since some steelmaking coals can be diverted to thermal uses, with the stock up 23 percent for the quarter, mostly in January, as the company navigated the prior 12 to 18 months well through good production and cost management, maintaining positive free cash flow and declaring a dividend of around 5 percent, or A$0.125 a share, in February. Seneca Financial Solutions favoured Stanmore as a coal opportunity where pessimism may have gone too far, combining low-cycle pricing with cheap equity valuations, an established producer with a strong management team, describing coal prices as having been on the nose for a couple of years after a big spike in 2022 tied to Russian coal supply coming out of the market following the Russia-Ukraine conflict.
It's a simple thesis, this one for us. It's low cycle pricing combined with cheap equity valuations. Stanmore is coking coal for steel making out of Queensland.
— Seneca Financial Solutions, Presentation, May 2026
An overhang removed, and the cycle turns
PM Capital said the stock rose 19 percent after confirmation that Anglo American's Queensland steelmaking coal assets would be sold to an alternate bidder, removing a potential overhang on Stanmore shares from a possible capital raise, and believes management made the right decision to pass on the opportunity given the strength and consistency of Stanmore's own mines. By August, PM Capital said the stock rose a further 19 percent as the coal sector emerges from a two-year price downturn, helped by European steelmakers restarting and reduced Chinese domestic supply, with Stanmore trading under 5 times earnings at spot coal prices.
Stanmore Resources rose 19% as the coal sector emerges from a two-year price downturn, helped by European steelmakers restarting and reduced Chinese domestic supply; it trades under 5x earnings at spot coal prices.
— PM Capital, Monthly Report, August 2026
What fund managers say they are watching next is whether the coal sector's emergence from its two-year downturn continues as European steelmakers restart and Chinese domestic supply stays reduced, delivery of continued operational consistency and cost discipline, further capital returns given reaffirmed strong free cash flow, and whether the roughly 5 times earnings valuation closes as the cycle turns further.
Questions
How did Stanmore Resources maintain positive cash flow during the coal downturn?
Stanmore Resources maintained operational consistency and disciplined cost management across its three Queensland Bowen Basin mines, avoiding the asset idling and deferred capital expenditure that forced some peers to cut back during the two-year steelmaking coal price downturn.
Why did Stanmore Resources shares rise after the Anglo American coal asset sale?
Stanmore Resources rose 19% after Anglo American's Queensland steelmaking coal assets were sold to an alternate bidder rather than Stanmore, removing a potential capital raise overhang and validating management's decision to pass on the acquisition opportunity.
How cheap is Stanmore Resources trading according to fund managers?
PM Capital notes Stanmore Resources trades under 5 times earnings at spot coal prices, even as the steelmaking coal sector emerges from a two-year price downturn helped by European steelmakers restarting production.
6 managers, 21 comments, with each manager's latest recorded position.
See SMR