

Universal Store's Youth Fashion Brands Prove Resilient to Rate Rises
Strong like-for-like growth across three brands and a less rate-sensitive youth customer base are helping Universal Store take market share through a tough retail backdrop.
21 Sep 2026 · 3 min read
In short
Universal Store Holdings delivered sales growth of 14% and net profit after tax growth of 22%, supported by like-for-like growth across its Universal, Perfect Stranger and Thrills brands.
Fairview Equity Partners and Pendal Group note the youth-focused customer base is less impacted by higher interest rates, with competitive tailwinds as peers rationalise their store footprints.
Yarra Capital Management sees continued strong like-for-like sales and a still-live store rollout story as worth holding through a tough retail backdrop, backed by 96% cash flow conversion over recent years.
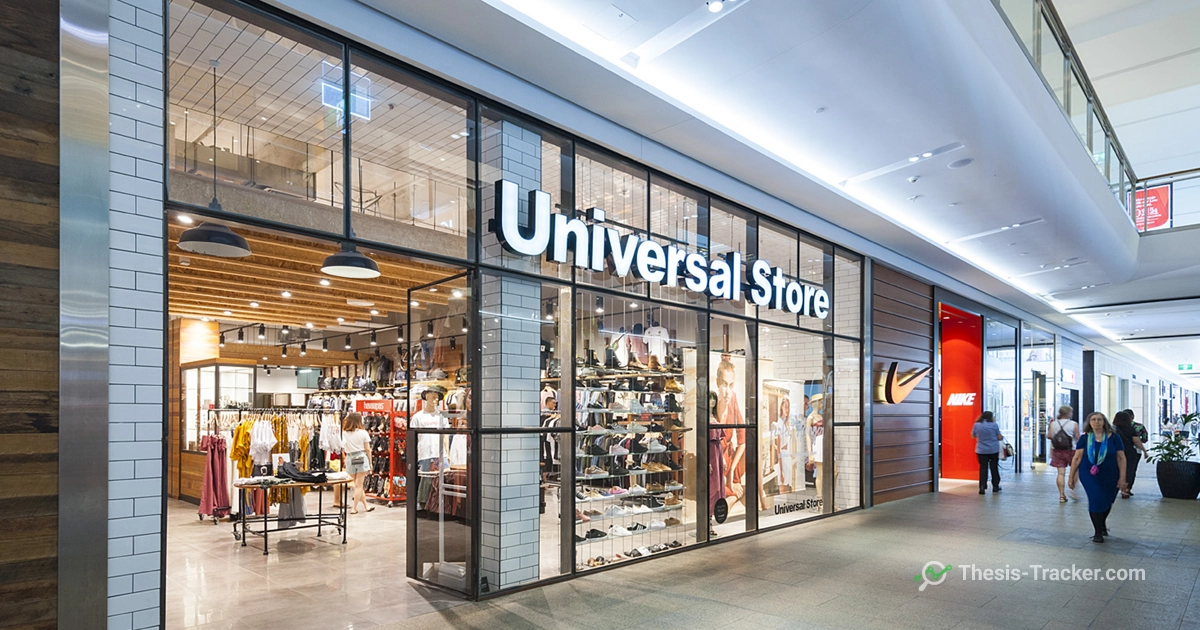
Universal Store Holdings, a youth-targeted apparel retailer with three brands including Universal, Perfect Stranger and Thrills, delivered strong like-for-like growth and industry-leading cash flow conversion, benefiting from a less rate-sensitive younger customer base and competitor closures freeing up market share, even as the broader retail backdrop remained tough.
A niche, disciplined specialty retail exposure
Ten Cap said Universal, on the smaller end, adds niche exposure to specialty retail, with its agile format and disciplined execution providing attractive leverage to a cyclical upswing in discretionary spending.
Strong results and industry-leading cash conversion
Perennial Partners said Universal Store reported a strong result, with sales up 14 percent and strong internal execution driving operating leverage, with net profit after tax up 22 percent, and the outlook remaining positive as it continues to take market share, with tailwinds from further store rollout and net cash of $38 million. Spheria Asset Management said the stock returned 16 percent over the month following the release of a strong first-half FY26 result, with revenue growing 14 percent, supported by both new store openings and solid like-for-like growth across all three brands, Universal, Perfect Stranger and Thrills, with gross margin improving through continued private-label penetration and disciplined promotional activity, describing a still fairly immature business with around 120 stores nationally and growing, well run with cash flow conversion around 96 percent over the last four to five years.
Revenue grew 14%, supported by both new store openings and solid like-for-like growth across all three brands - Universal, Perfect Stranger and Thrills. Gross margin improved through continued private-label penetration and disciplined promotional activity.
— Spheria Asset Management, Monthly Report, February 2026
A less rate-sensitive customer base holds up
Fairview Equity Partners said it likes youth apparel retailer Universal Store Holdings given its customer base is less impacted by higher rates. Pendal Group said the stock fell 6.2 percent even as sales remained resilient, up 8 percent in the second half to date, broadly consistent with 7 percent in January and February, with key brands continuing to benefit from exposure to a more resilient youth consumer despite a higher interest rate and inflationary backdrop, also seeing competitive tailwinds as several peers rationalise their store footprints. Ten Cap said Universal continues to offer an attractive balance of value and growth.
Key brands (Universal Store and Perfect Stranger) continue to benefit from exposure to a more resilient youth consumer, despite a higher interest rate and inflationary backdrop. The group is also seeing competitive tailwinds, with several peers rationalising store footprints.
— Pendal Group, Newsletter, May 2026
Continued execution through a tough retail backdrop
Yarra Capital Management said it was impressed by continued strong like-for-like sales in the fickle youth fashion segment amid competitor failures, an ongoing store rollout opportunity, and management working through disruption in wholesale channels, seeing the company as executing well enough to hold through a tough retail backdrop. Later, the fund said Universal Store delivered another very strong result with continued good like-for-like growth, a still-live store rollout story, and improving execution as wholesale-channel disruption from competitor closures worked through.
Universal Store delivered another very strong result with continued good like-for-like growth, a still-live store rollout story, and improving execution as wholesale-channel disruption from competitor closures works through — worth holding despite a tough retail backdrop given its execution and 'right price, right time' positioning.
— Yarra Capital Management, Article, September 2026
What fund managers say they are watching next is continued like-for-like sales growth in the fickle youth fashion segment, delivery of the ongoing store rollout opportunity, resolution of wholesale-channel disruption from competitor closures, and whether the resilient, less rate-sensitive youth consumer base continues supporting growth through the tough retail backdrop.
Questions
How strong has Universal Store Holdings' recent growth been?
Universal Store Holdings reported sales up 14% and net profit after tax up 22%, supported by like-for-like growth across all three of its brands: Universal, Perfect Stranger and Thrills.
Why is Universal Store Holdings' customer base considered resilient?
Fairview Equity Partners and Pendal Group note the youth-focused customer base is less impacted by higher interest rates, with sales remaining resilient despite a higher interest rate and inflationary backdrop.
How is Universal Store Holdings benefiting from competitor struggles?
Pendal Group notes competitive tailwinds as several peers rationalise their store footprints, while Yarra Capital Management sees an ongoing store rollout opportunity as wholesale-channel disruption from competitor closures works through.
11 managers, 16 comments, with each manager's latest recorded position.
See UNI