Search All
MIN
Search by Name
Search by Ticker
ASX:S32
•
Metals and Mining
South32's $5.6bn Alcoa Deal Turns It Into a Focused Base Metals Growth Story
Selling the aluminium business trades some diversification for a cleaner, higher-margin copper, zinc and silver portfolio fund managers are backing.
TT
Thesis Tracker
31 August 2026
•
3 min read
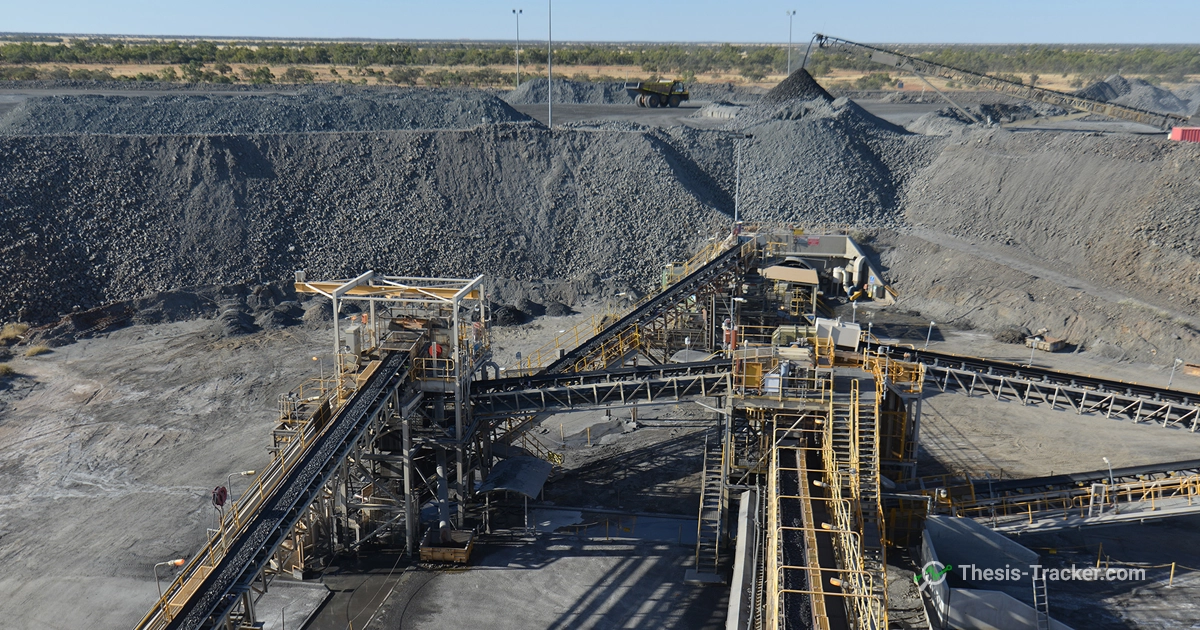
South32 is selling its aluminium business to Alcoa for up to US$5.6bn, refocusing on copper and base metals. Fund managers are largely on board.
In Short
South32 agreed to sell its aluminium value chain to Alcoa for up to US$5.6 billion, refocusing the business on higher-margin base metals including copper, zinc, silver and lead.
The stock rose about 17% in July on the deal and a strong June-quarter production report, with Sierra Gorda copper mine distributions hitting a record US$401 million.
Fund managers including Pendal Group expect substantially higher shareholder returns once the Alcoa sale closes in the second half of FY27, with Sierra Gorda and the Hermosa project now the key drivers of valuation.
South32 spent July transforming itself from a diversified miner into a focused base-metals growth story, agreeing to sell its aluminium value chain to Alcoa for up to US$5.6 billion in a deal fund managers have almost universally welcomed, even though it comes with an ironic side effect for a stock some had specifically liked because it wasn't just another single-commodity miner.
A deal that simplifies the business, even as it narrows it
Maple-Brown Abbott had picked South32 specifically for its diverse commodity mix and its lack of exposure to iron ore, and acknowledged the Alcoa transaction, which sold off close to 40 percent of group earnings tied to the alumina and aluminium value chain, leaves the business with less diversification than before, primarily a copper story with smaller contributions from silver, lead and manganese, though still attractively valued for the suite of minerals that remain. Pendal Group laid out the mechanics: consideration of up to US$5.6 billion made up of US$3.1 billion in cash, US$1 billion in Alcoa shares, assumed debt and up to US$750 million of commodity-linked contingent payments, alongside roughly US$1.2 billion of rehabilitation liabilities transferred to Alcoa. Pendal views the deal very positively, arguing it exits a lower-growth downstream business and refocuses South32 on higher-margin base metals, copper, zinc, silver and lead, that trade at materially higher valuation multiples, while leaving the company with pro forma net cash of around US$3.8 billion.
Following the positive share price reaction, we still see potential for further rerating as S32 becomes a cleaner pure-play base metals growth story.— Pendal Group, Newsletter, July 2026
Solaris Investment Management, previously underweight the stock, initiated a new position after the announcement, viewing South32 as a simplified business now focused on base metals assets in tier one jurisdictions. Endeavor Asset Management noted the deal was announced alongside a chief executive transition, and traded the position actively through the month, trimming early and rebuilding later as conviction firmed.
The operational story behind the rally
The deal landed alongside a strong June quarter production report. Endeavor Asset Management detailed aluminium production running ahead of guidance and the Sierra Gorda copper mine coming in 2 percent above target, delivering record annual distributions to South32 of US$401 million, alongside approval of a fourth grinding line expected to lift copper equivalent production by around 30 percent from FY31. The combination made South32 the largest single contributor to several funds' performance in July, with Perennial Partners and Endeavor Asset Management both citing the roughly 17 percent monthly gain as a standout.
Patient on payouts today, bigger returns expected once the deal closes
South32's August FY26 result came in broadly in line, with underlying EBITDA 2 percent ahead of expectations, according to Pendal Group. The company maintained its 40 percent dividend payout ratio rather than following much of the mining sector toward higher payouts this reporting season, though it extended its buyback for another year. Pendal noted South32's net cash position will jump materially once the Alcoa sale closes in the second half of FY27, meaning shareholders should expect substantially higher capital returns from that point. FY28 earnings estimates edged higher on a 9 percent beat to production guidance at Sierra Gorda, which Pendal now treats as the single largest driver of its valuation, followed by the Hermosa project in the United States.
Sierra Gorda remains key to S32, representing 40% of our valuation, followed by the Hermosa project at approximately 30%.— Pendal Group, Newsletter, August 2026
With the aluminium sale still to formally close, fund managers say the things to watch next are completion of the Alcoa transaction and the scale of capital returns that follow, continued outperformance at Sierra Gorda as the fourth grinding line ramps toward its FY31 production lift, and progress on the Hermosa project, now a much larger share of South32's overall valuation in a business that has deliberately made itself smaller and simpler to grow faster.
Price
Price
Price
Price
Market cap
12 managers
Sector
12 managers
Fund managers
12 managers
First covered
12 managers
Last updated
12 managers
Company Details
ic
Ipsum Capital
6 comments
ic
Amet Funds
4 comments
ic
Dolor
3 comments
Top Investors Covering MIN
Related Themes
Frequently asked questions
Frequently asked questions
Why did South32 sell its aluminium business to Alcoa?
South32 sold its aluminium value chain assets to Alcoa for up to US$5.6 billion to exit a lower-growth downstream business and refocus on higher-margin base metals such as copper, zinc, silver and lead, which trade at materially higher valuation multiples.
How much cash will South32 have after the Alcoa deal?
Pendal Group estimated the transaction leaves South32 with pro forma net cash of around US$3.8 billion, with shareholders expected to see substantially higher capital returns once the sale completes in the second half of FY27.
What is now the biggest driver of South32's valuation?
Pendal Group views the Sierra Gorda copper mine as the largest single driver of South32's valuation at around 40%, followed by the Hermosa project in the United States at approximately 30%.