Search All
MIN
Search by Name
Search by Ticker
ASX:NST
•
Metals and Mining
Why fund managers still back Northern Star Resources' growth profile
Northern Star Resources delivered a record FY25 profit even as disappointing FY26 guidance tested investor patience ahead of a major KCGM mill expansion.
TT
Thesis Tracker
23 July 2026
•
6 min read
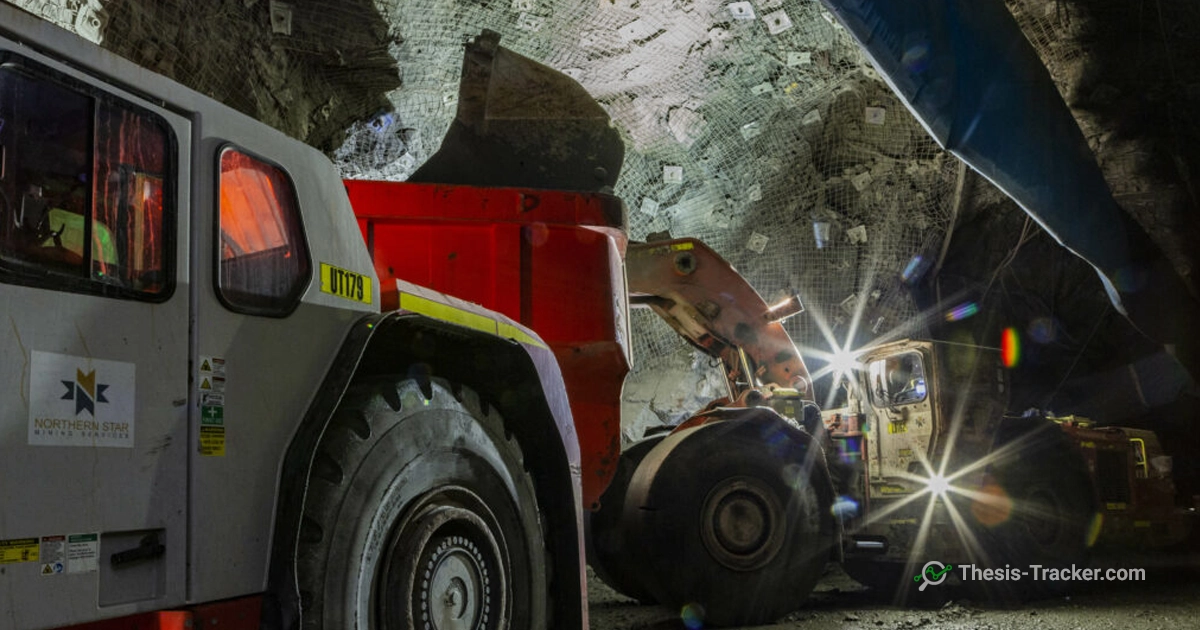
Fund managers on Northern Star Resources: a record FY25 profit of $1.3 billion, a KCGM mill expansion to 27Mtpa, and a disappointing FY26 production guidance update.
In Short
Northern Star Resources reported FY25 revenue of $6.4 billion and net profit more than doubling to $1.3 billion, lifting its dividend to 30 cents a share.
The KCGM mill expansion from 13 million to 27 million tonnes per annum remains on track for commissioning in early FY27, seen as a step change for production and free cash flow.
Ten Cap rotated gold exposure from Newmont into Northern Star, viewing recent production downgrades as temporary ahead of an expected operational normalisation.
Gold producer Northern Star Resources delivered a record FY25 financial result even as its FY26 production guidance disappointed the market, with Yarra Capital Management's August 2025 Monthly Report detailing revenue of $6.4 billion and net profit more than doubling to $1.3 billion, while lifting its dividend to 30 cents a share, a result the manager attributed to what it considers the most robust organic production growth profile in the gold sector.
A transition year overshadowed by KCGM's mill expansion
Tyndall Asset Management's July 2025 Monthly Report detailed the source of the initial disappointment: FY26 projections featured slightly reduced volumes alongside elevated production costs and growth capital expenditure, even as the manager continued to see substantial value from underground development ramping up, KCGM's reconfirmed target of 900,000 ounces annually by FY29, and the unwinding of the company's hedgebook increasing exposure to spot gold prices. Pendal Group's October 2025 Newsletter detailed the centrepiece of that growth story: the KCGM mill expansion from its current 13 million tonnes per annum to 27 million tonnes per annum, remaining on track for commissioning in early FY27 and expected to deliver a step change in production and free cash flow.
We believe that Northern Star has the most robust organic production growth profile in the gold sector. Operational excellence, combined with strong organic growth, underpins our overweight position.— Yarra Capital Management, Monthly Report, August 2025
Antares Capital's September 2025 Monthly Report detailed a relief rally following site visits to the company's Western Australian operations, with the market coming away more comfortable on the cost and capex outlook after a series of recent disappointments in that area. Ten Cap's September 2025 report detailed rotating gold exposure from Newmont into Northern Star specifically to capture relative value, viewing the recent production downgrades as temporary ahead of an expected normalisation in operational performance.
What managers are watching next
Pendal Group's September 2025 report offered a useful comparison point, noting the fund's primary gold exposure through Evolution Mining had a higher free cash flow yield than Northern Star, even though Northern Star's production growth outlook was considered superior, illustrating the trade-off managers weigh across the sector. With the KCGM mill expansion and the Hemi project both representing major medium-term production catalysts still to be delivered, the pace of execution on both remains the central factor for managers assessing whether Northern Star's premium growth profile justifies its valuation relative to gold sector peers.
Price
Price
Price
Price
Market cap
12 managers
Sector
12 managers
Fund managers
12 managers
First covered
12 managers
Last updated
12 managers
Company Details
ic
Ipsum Capital
6 comments
ic
Amet Funds
4 comments
ic
Dolor
3 comments
Top Investors Covering MIN
Related Themes
Frequently asked questions
Frequently asked questions
Why did Northern Star Resources' share price fall in July 2025?
Northern Star Resources underperformed after providing FY26 production and cost guidance that fell short of market expectations, featuring slightly reduced volumes alongside elevated production costs and growth capital expenditure.
What is Northern Star Resources' KCGM mill expansion?
The KCGM mill expansion will increase processing capacity from 13 million tonnes per annum to 27 million tonnes per annum, remaining on track for commissioning in early FY27, and is expected to deliver a significant step change in production and free cash flow.
How does Northern Star Resources compare with Evolution Mining as a gold exposure?
Pendal Group notes Evolution Mining has a higher free cash flow yield than Northern Star Resources, though Northern Star is considered to have a superior production growth outlook, illustrating a trade-off fund managers weigh across the sector.